
What landed in our inbox this week
Across VC newsletters tracked, one thing became clear: this week reset what investors think AI is actually worth, while regulators in three jurisdictions moved in completely different directions on crypto.
28 unique VCs published. AI dominated the volume. Infrastructure followed. The dominant sentiment across all sources was neutral with a bullish AI undercurrent - funds aren’t celebrating yet, but they’re not running for the exits either.
Top trending names: Pluralis, Quantinuum, tea Protocol.
1. The AI valuation curve is no longer normal — and your raise will be priced against it whether or not it should be.
Anthropic at $965B means every Series A multiple gets benchmarked against a number that doesn’t reflect your stage. If you’re pitching, prepare for partners to anchor on the wrong comps. Have the answer ready: here’s why Anthropic’s revenue trajectory isn’t relevant to ours, and here’s the comp that is.
2. Distribution is the moat. Model performance is the table stake.
Benedict Evans called it “1997 for AI” on Lenny’s podcast this week. The thesis lining up across multiple newsletters: as AI capabilities commoditize, the durable moat shifts from “we have a better algorithm” to “we control access to the user.” If you’re building AI tooling without an embedded distribution channel, you’re competing on a dimension that’s losing value fast.
3. Decentralized AI infrastructure is becoming investable.
Pluralis at $7.6M from USV and CoinFund is small but matters because of who’s writing the check. The decentralized training thesis used to be a crypto sideshow. With EpochAI data showing 20x annual scaling, real VCs are now positioning. For founders in the AI infra layer - particularly those touching crypto rails - this is a window opening.
4. Regulatory arbitrage is real this quarter, and timing matters.
Japan moves forward on stablecoins June 1. UK frames their full crypto regulation for October 2027. US House aggressively investigates prediction markets June 5. Three jurisdictions, three different speeds, three different appetites. If you’re building in crypto-adjacent categories, your incorporation jurisdiction and licensing strategy is now a real moat or a real liability - not a future problem.
5. Public market exits are not back, but the doors are unlocking selectively.
Quantinuum’s IPO on June 3 is the bellwether to watch. If it prices well and trades clean, expect a small wave of deep-tech follow-ons. If it disappoints, the IPO window quietly closes again for everyone but the SpaceX/OpenAI/Anthropic tier. For founders at Series B+, the answer to “should I raise more private or wait for the window” depends on this datapoint in 7 days.
1. The death of the seat: agents replacing SaaS is now consensus
The "AI agents will replace SaaS" thesis went from contrarian to consensus in about six months.
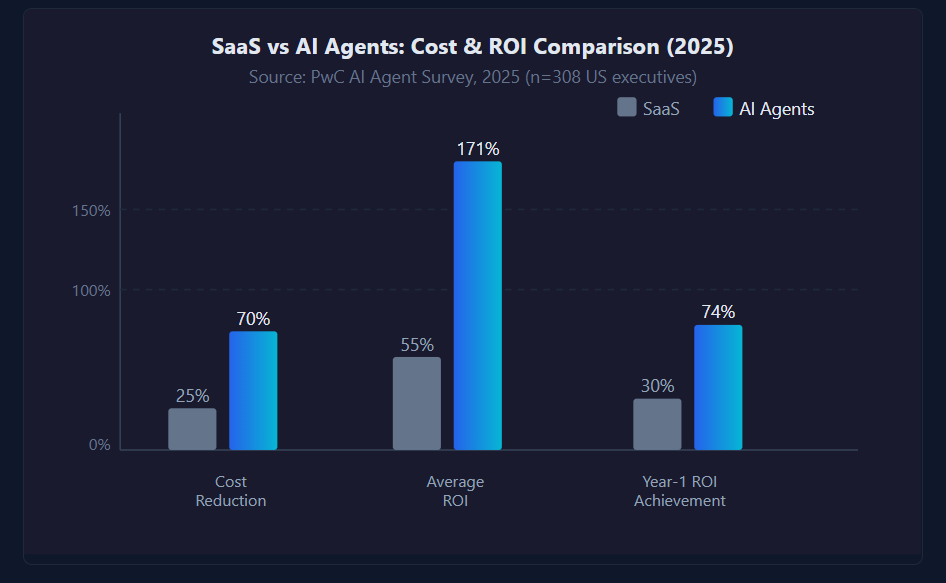
In February, $285 billion in software market cap vanished in a single trading session - ServiceNow, Salesforce, Intuit all down 7-11%. The trigger wasn't a recession or regulation. It was Anthropic releasing Claude Cowork enterprise plugins that let one person automate work previously requiring 5-10 separate SaaS subscriptions. The "SaaSpocalypse" tag stuck.
This week, the Canonical Capital piece "Eyes Are a Tax" articulated where this is heading: the browser-and-dashboard UX is structurally inefficient. The terminal, the place where work actually executes, won. Software companies whose value proposition is "we give you a nice interface to click buttons" are competing against agents that just do the thing.
Madrona's letter this week called out the same thing from a different angle. Their take: "the next AI bottleneck is security", meaning enterprises are ready to deploy agents broadly, but the friction now is around governance, not capability.
Even Lenny's interview with Benedict Evans hit the same note. Evans called this "a 1997 internet moment", meaning we're at the point where everyone agrees the technology is real, the only argument is about where the value accrues.
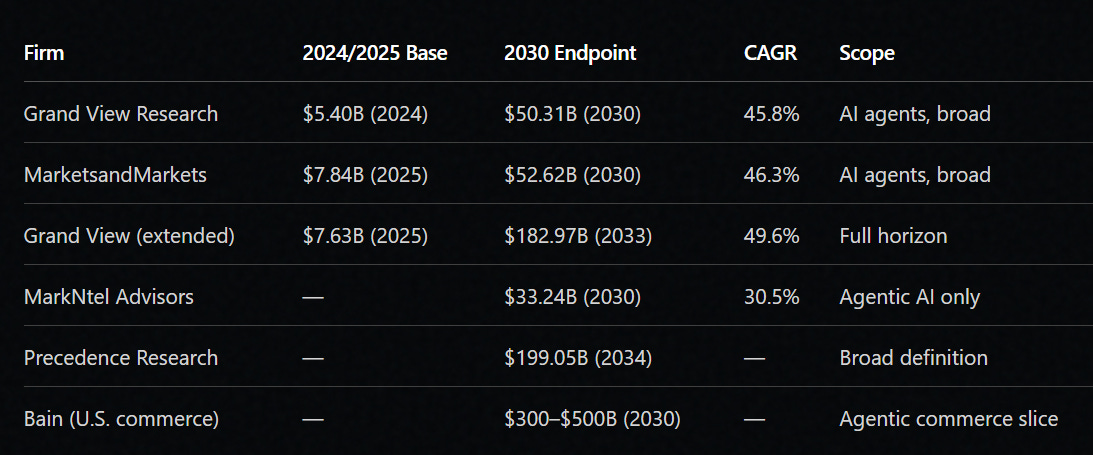
Bessemer just disclosed an average Series A check size of $18.3M, with deep concentration in AI-native enterprise companies. The enterprise AI agent market grew from $5.25B in 2024 to ~$7.84B in 2025, projected to hit $52.62B by 2030.
What this means for founders:
If you're pitching anything SaaS-shaped right now, your deck needs to answer one question: what do you charge for that an agent can't replace?
It's not enough to say "we have AI features” because every SaaS has AI features. The real question is whether the agent version of your product replaces you or runs on top of you.
The founders raising successfully this quarter are building the infrastructure agents call out to. Look at Cognition (reported by Neo this week): $1B raise at $26B valuation, $492M run-rate. They're the agent layer for engineering work. That's the model VCs are now writing checks against.
2. The secondary market is now bigger than the IPO market
US venture secondary transaction value hit $112.2 billion annualized this quarter. That's larger than VC-backed IPOs over the same period.
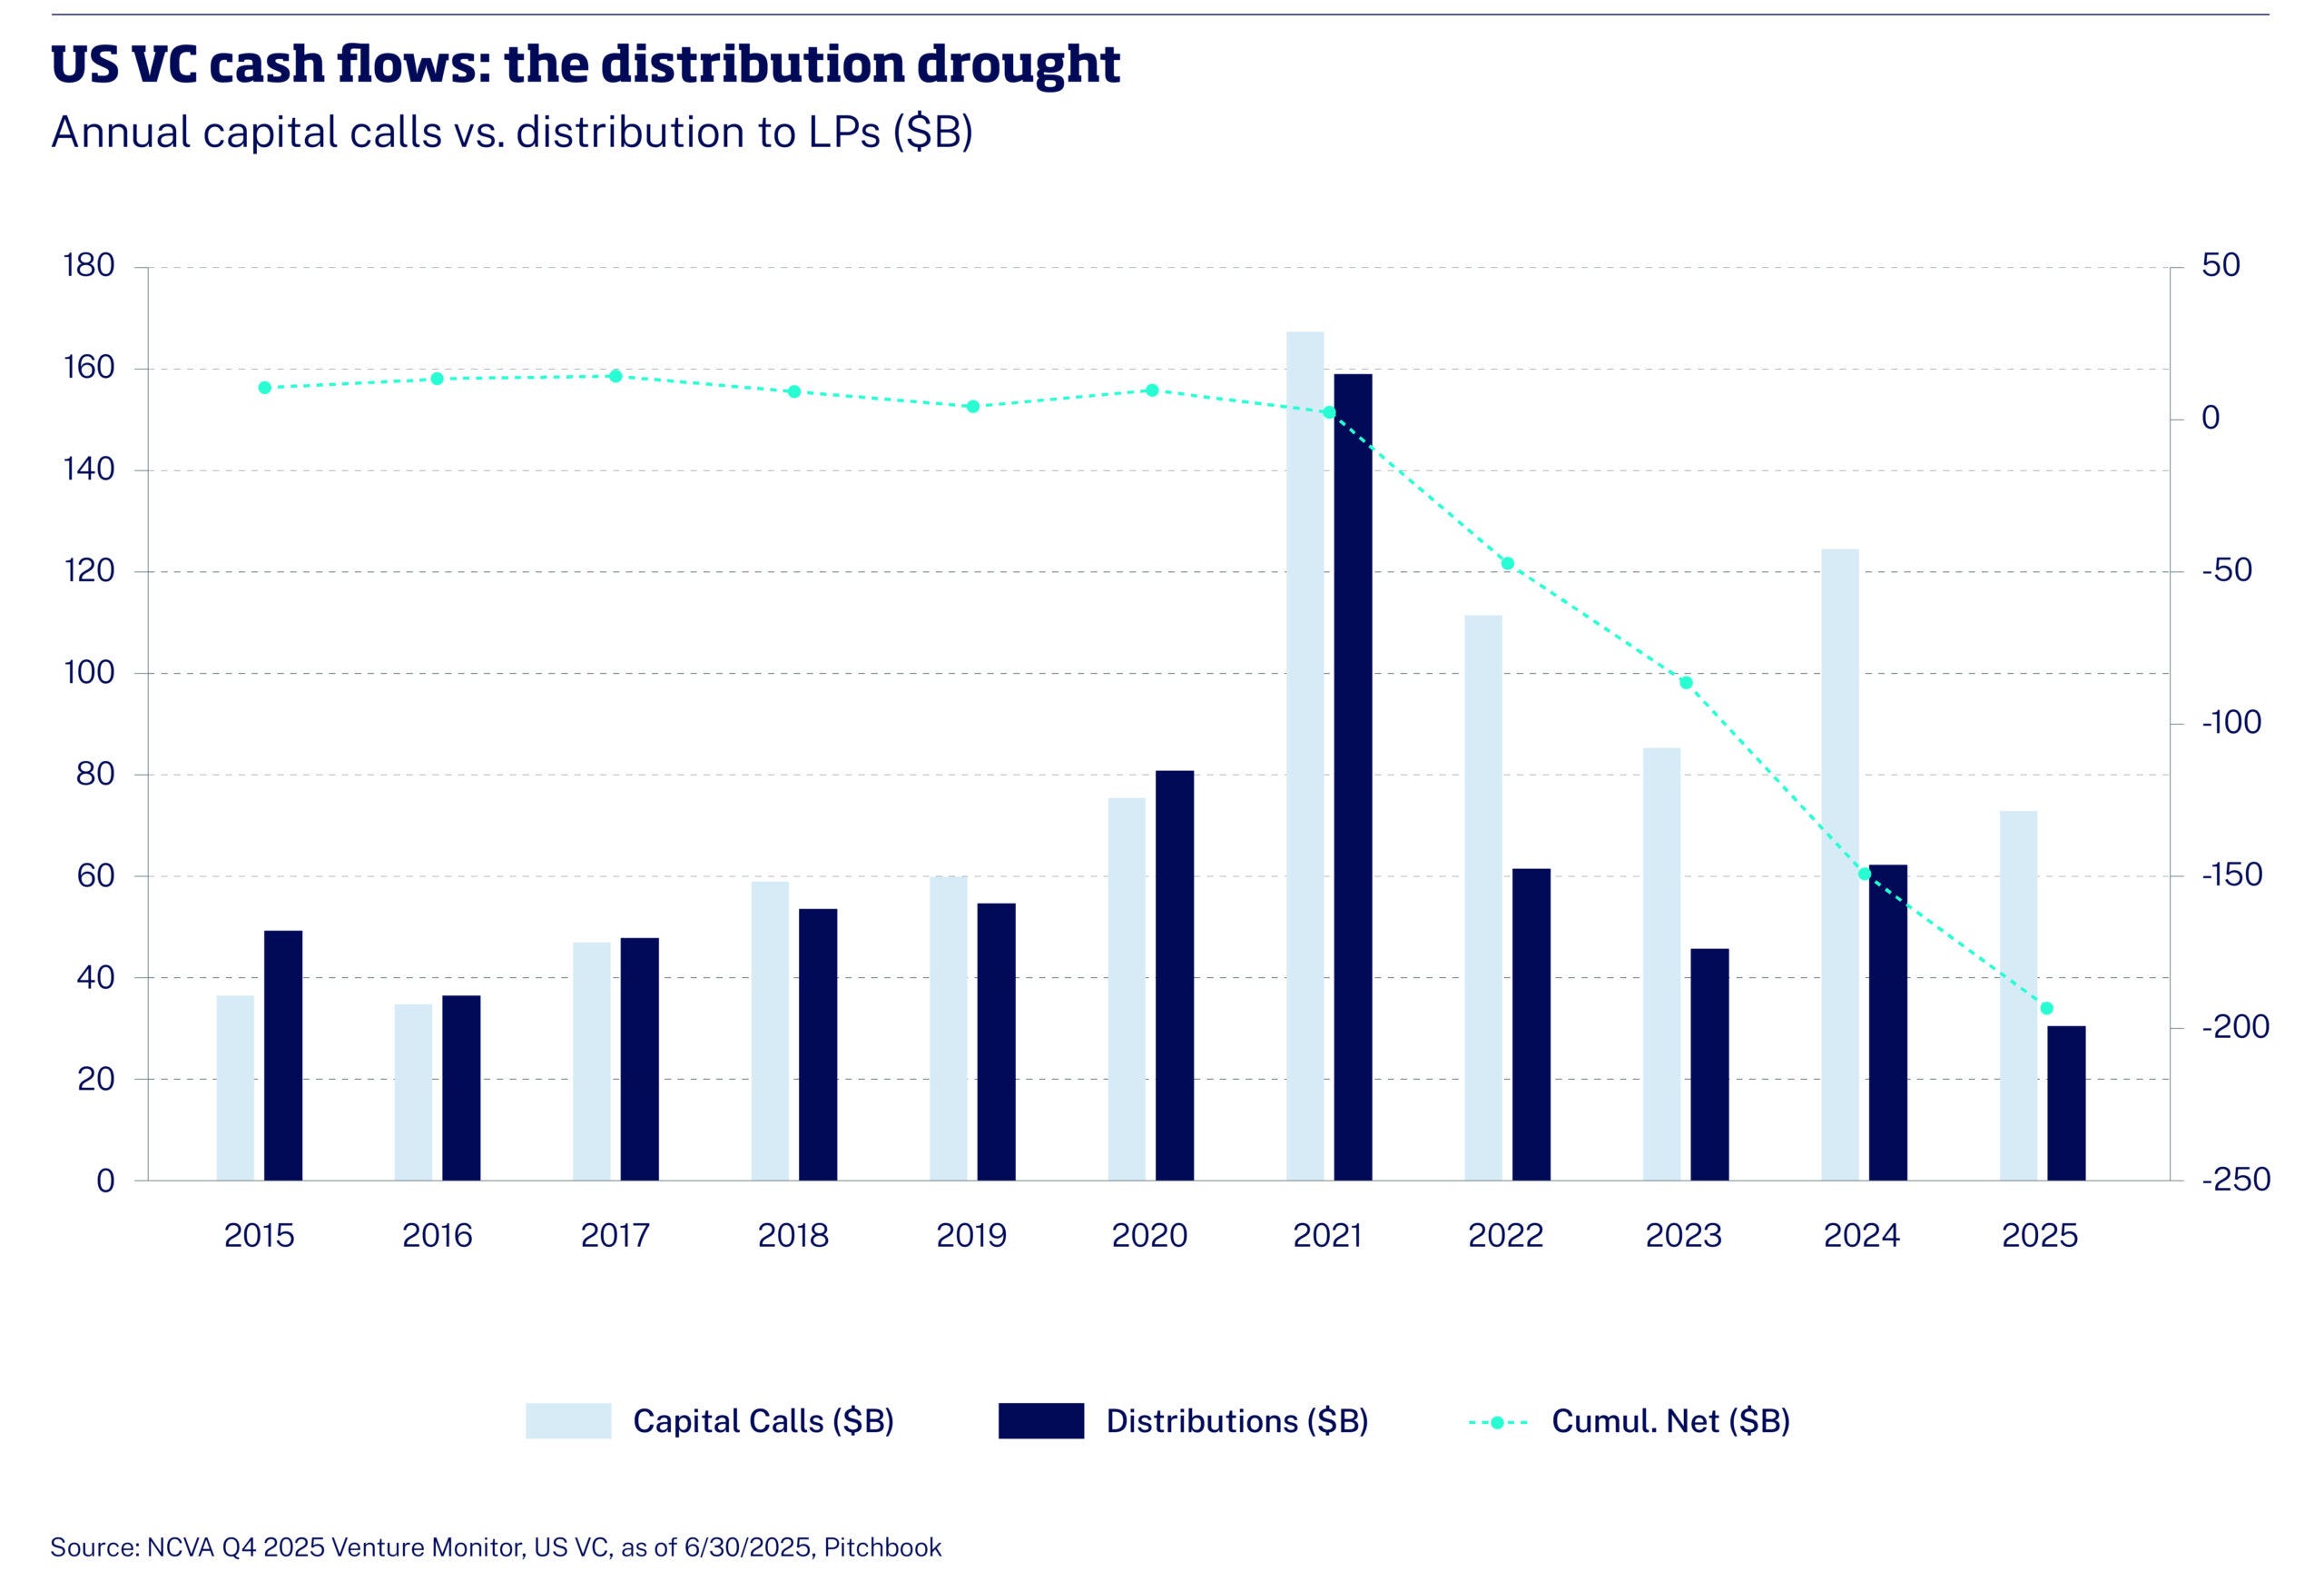
The PitchBook Q1 2026 outlook puts the question: what happens to a $112 billion secondary market when its most valuable constituents (SpaceX, OpenAI, Anthropic) go public? The top 20 names currently capture 81% of secondary trading value. Once they exit, returns get held in lockup, get directed toward addressing venture's four-year distribution deficit, and don't recycle back into secondaries for a long time.
So we're in an unusual moment. Secondaries are bigger than IPOs, but they're also concentrated in the same names that are about to leave the secondary market. The middle of the unicorn pool, thousands of companies, still has no real liquidity path.
20VC's newsletter this week touched on the institutional adoption angle. Goldman Sachs bought Industry Ventures last year. Morgan Stanley acquired EquityZen. Schwab moved for Forge Global. Secondary SPVs increased 682% from 2023. This is becoming infrastructure, not workaround.
What changed: over 40% of active unicorns raised their first round more than a decade ago. Cumulative cash flows from US venture funds to LPs have been negative by $197 billion since 2022. Holding period for VC investments is now 10+ years on average. Equity became a long-term retention mechanism that needs liquidity built in.
If your investors are pushing you toward profitability and away from another priced round, the reason might be that they need to set up a secondary in 12-18 months and need a clean cap table to do it.
If you have early employees who've been with you 4+ years, tender offers are now a realistic retention tool. The Founder Collective letter this week made the point that "the founder factories" of the next decade will be companies that built liquidity events for their teams before the IPO. That's a competitive advantage in hiring.
If you're at Series B or later, ask your lead what their secondary strategy is. If they don't have one, that's a yellow flag - they may not understand the new exit reality and you'll be the one pushing them to figure it out.
All of this was pulled from the Byblos live feed - 600+ VC firms, 27500+ newsletters, one place.
See what else came in today at byblos.digital →
3. Three jurisdictions on crypto regulation
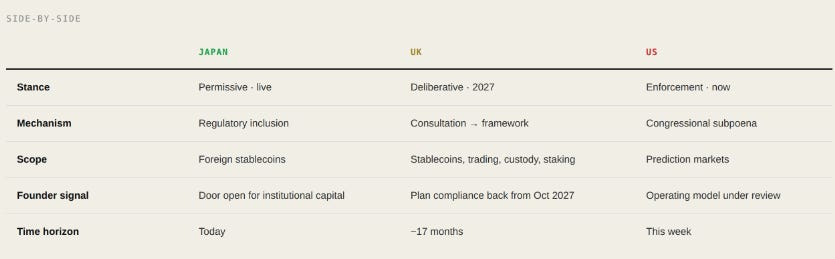
Japan, June 1. The FSA formally included foreign trust-type stablecoins in its electronic settlement regulatory framework. As of this week, foreign stablecoin services have a legal basis in Japan, with equivalency standards for providers. This is the clearest institutional path for stablecoin adoption in a major economy, and the template other G7 jurisdictions are watching.
United Kingdom, June 3. The UK FCA’s consultation on a comprehensive crypto framework closes today. The iea - covering stablecoins, trading, custody, and staking -is set to take effect October 25, 2027. The UK is going slower than Japan but building broader. The deliberate pace suggests they want one well-designed framework rather than incremental rules.
United States, June 5. The House Oversight Committee’s subpoena deadline for Polymarket and Kalshi hits this Friday. The committee is demanding full documentation on identity verification, geographic restrictions, and anomalous transaction monitoring, framed around national security concerns about suspicious activity preceding military and geopolitical events. This is the most aggressive regulatory action on prediction markets to date.
Three completely different regulatory philosophies.
Japan opens the door for stablecoin issuers. The UK is building a fence carefully and slowly. The US is sending out subpoenas with national security framing attached.
What’s notable is the speed and the simultaneity. Three major jurisdictions making consequential moves in the same week, while Telegram became the largest validator on TON and the US Treasury continues digesting last year’s GENIUS Act. The regulatory environment isn’t drifting toward consensus. It’s hardening into incompatible tracks.
For stablecoin issuers and infrastructure: Japan just became the most legible market. Mastercard’s $1.8B BVNK acquisition this week is a tell - incumbents are positioning for the regulated stablecoin window opening across G7 markets.
For prediction market operators and anyone doing event-based trading: the Polymarket/Kalshi subpoena response on June 5 will set the operating model for the entire category in the US for the next 18 months. If they push back hard, expect formal enforcement. If they comply, expect every prediction market to adopt similar identity verification and geographic restriction infrastructure as table stakes.
For DeFi protocol founders generally: jurisdiction arbitrage is real this quarter, but it has a cost. Operating from a clear-rules jurisdiction (Japan, UK by 2027) costs more in compliance but unlocks institutional capital. Operating from a permissive jurisdiction is faster and cheaper but caps your eventual fundraising ceiling at the level where institutional LPs get uncomfortable.
One thing worth flagging: G7 regulatory frameworks tend to move from “consultation” to “enforcement” in 18-month cycles. Japan’s framework is live now. The UK framework is targeted for October 2027 - that’s the window where founders building today need to be compliant or grandfathered.
4. Fundraising itself is being rebundled
This is the practical consequence of everything above, and it's the most underreported shift in the venture stack.
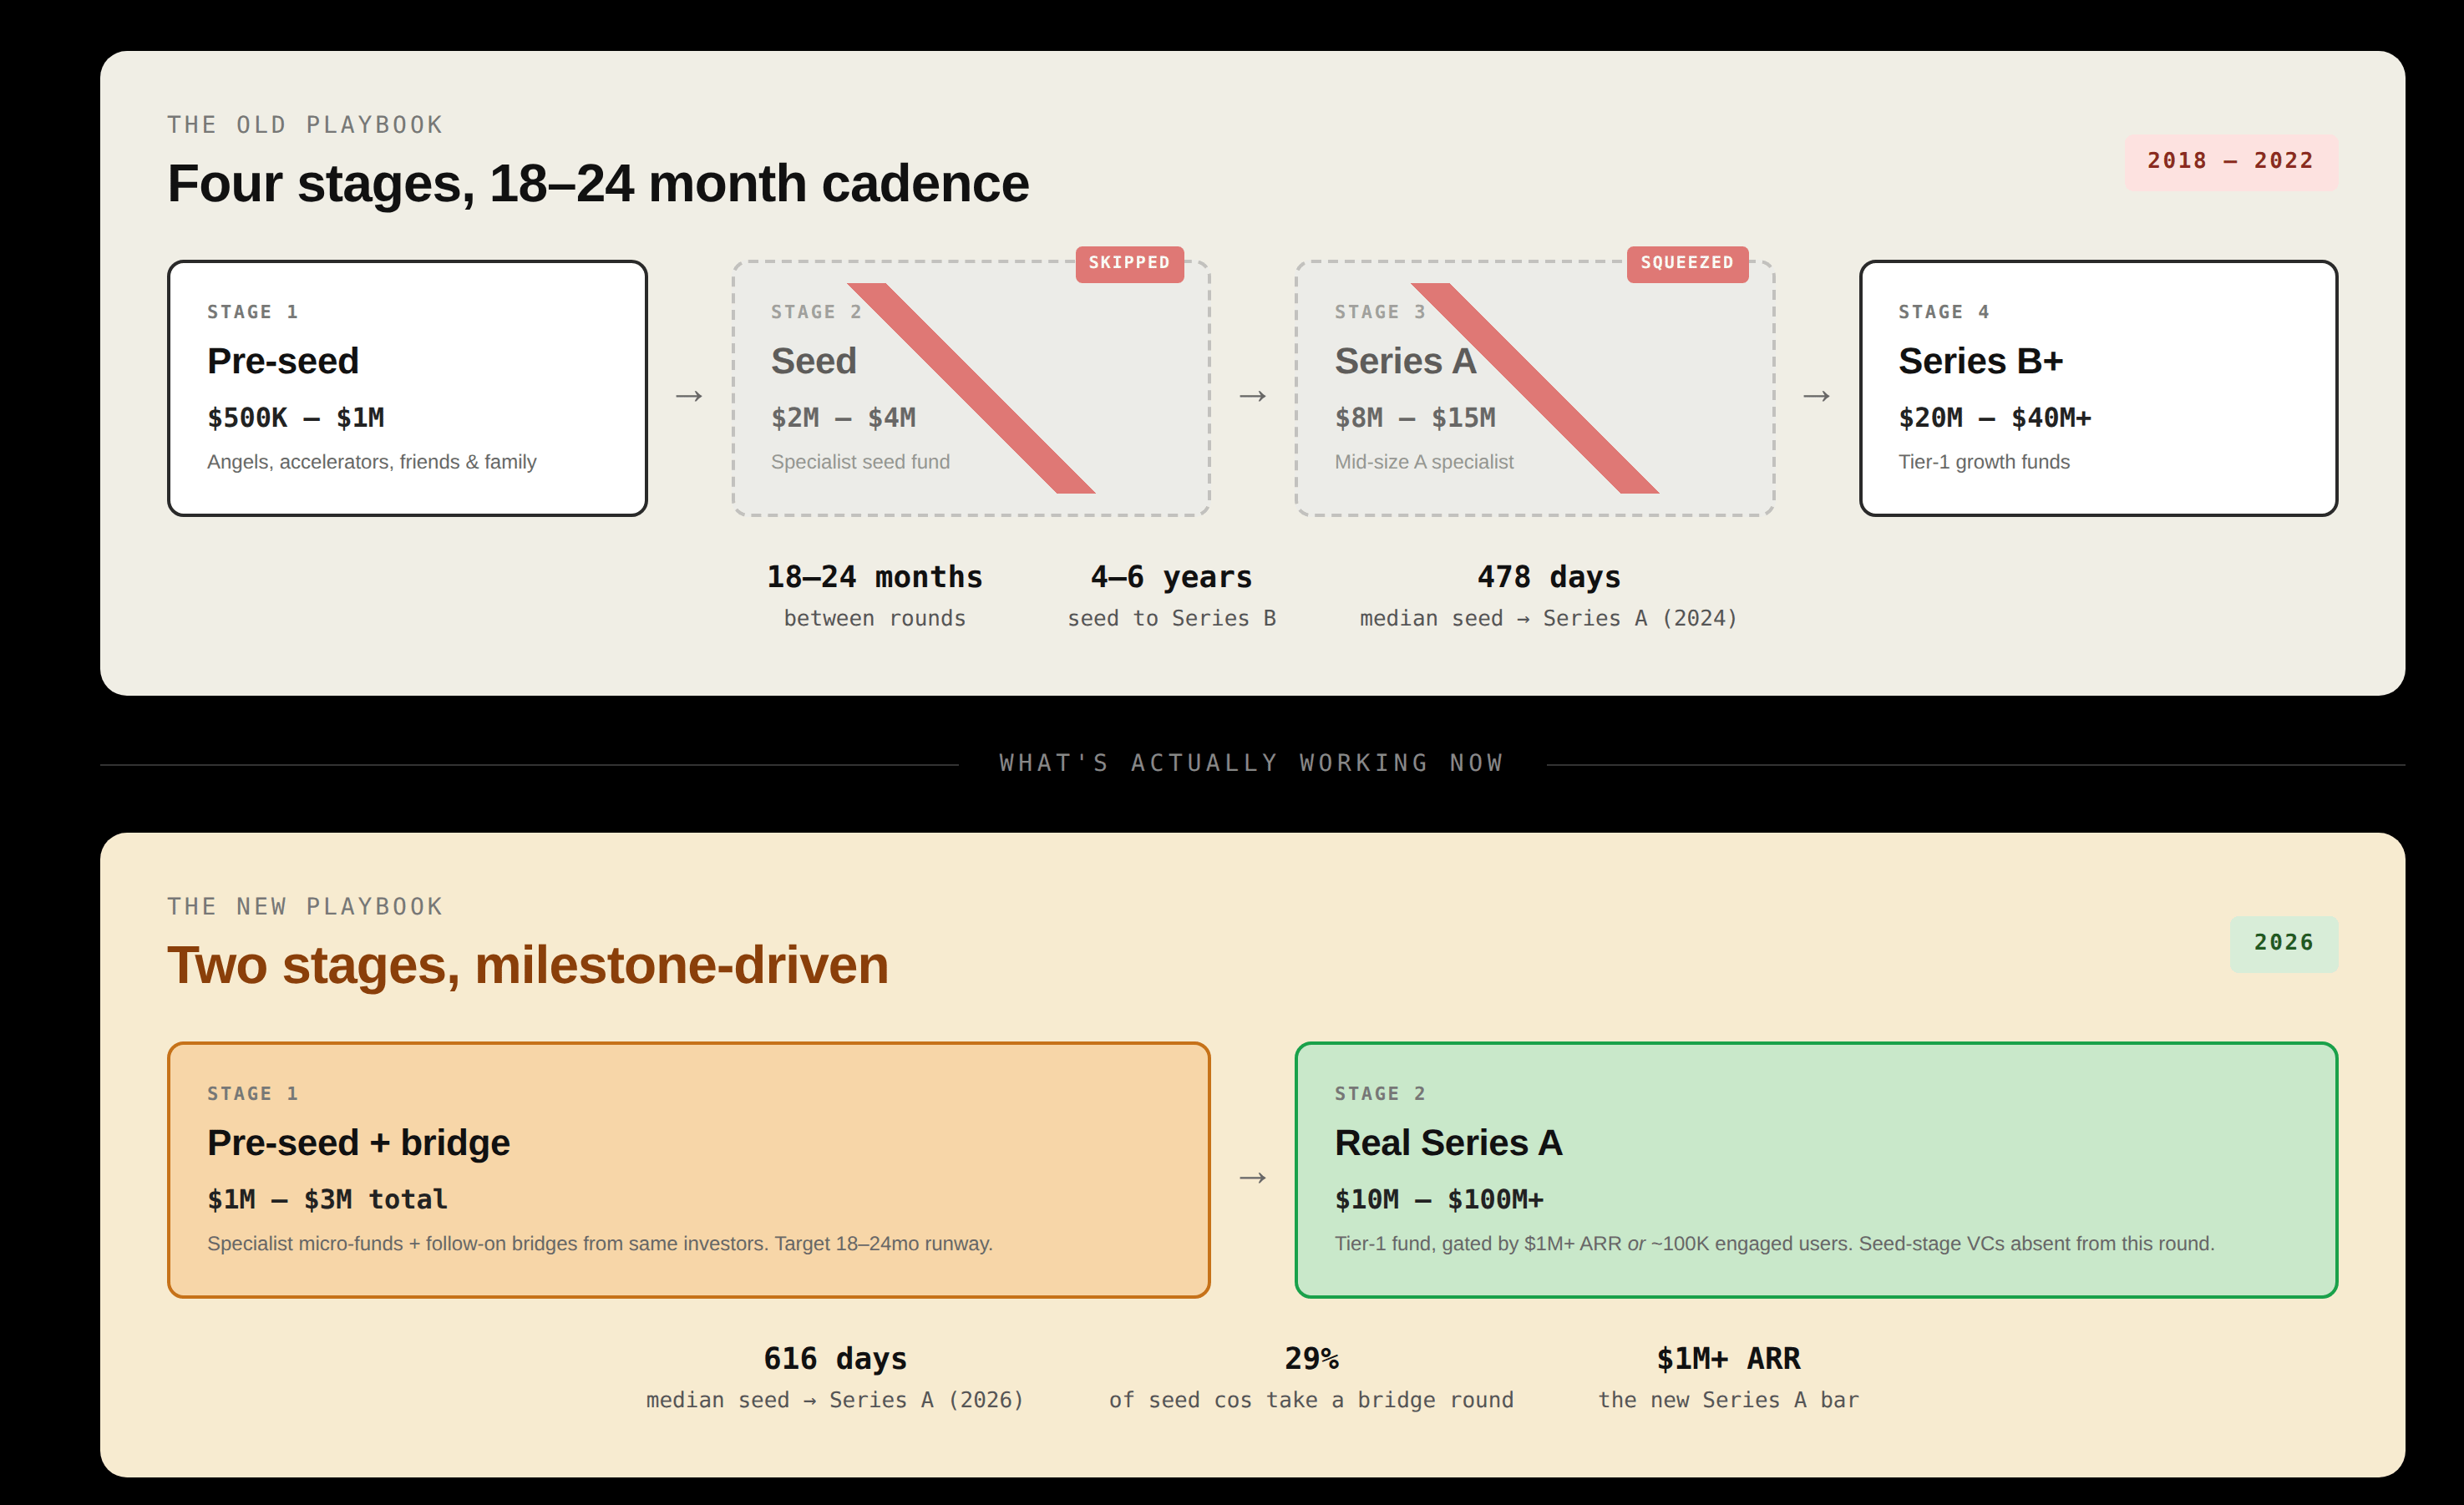
The old playbook: pre-seed (~$500K-1M) → seed ($2-4M) → Series A ($8-15M) → Series B ($20-40M) → growth. Each round on a ~18-24 month cadence.
The new playbook that's actually working in 2026: pre-seed → bridge → Series A directly, with the seed round either skipped or absorbed into either an extended pre-seed or a pre-A bridge.
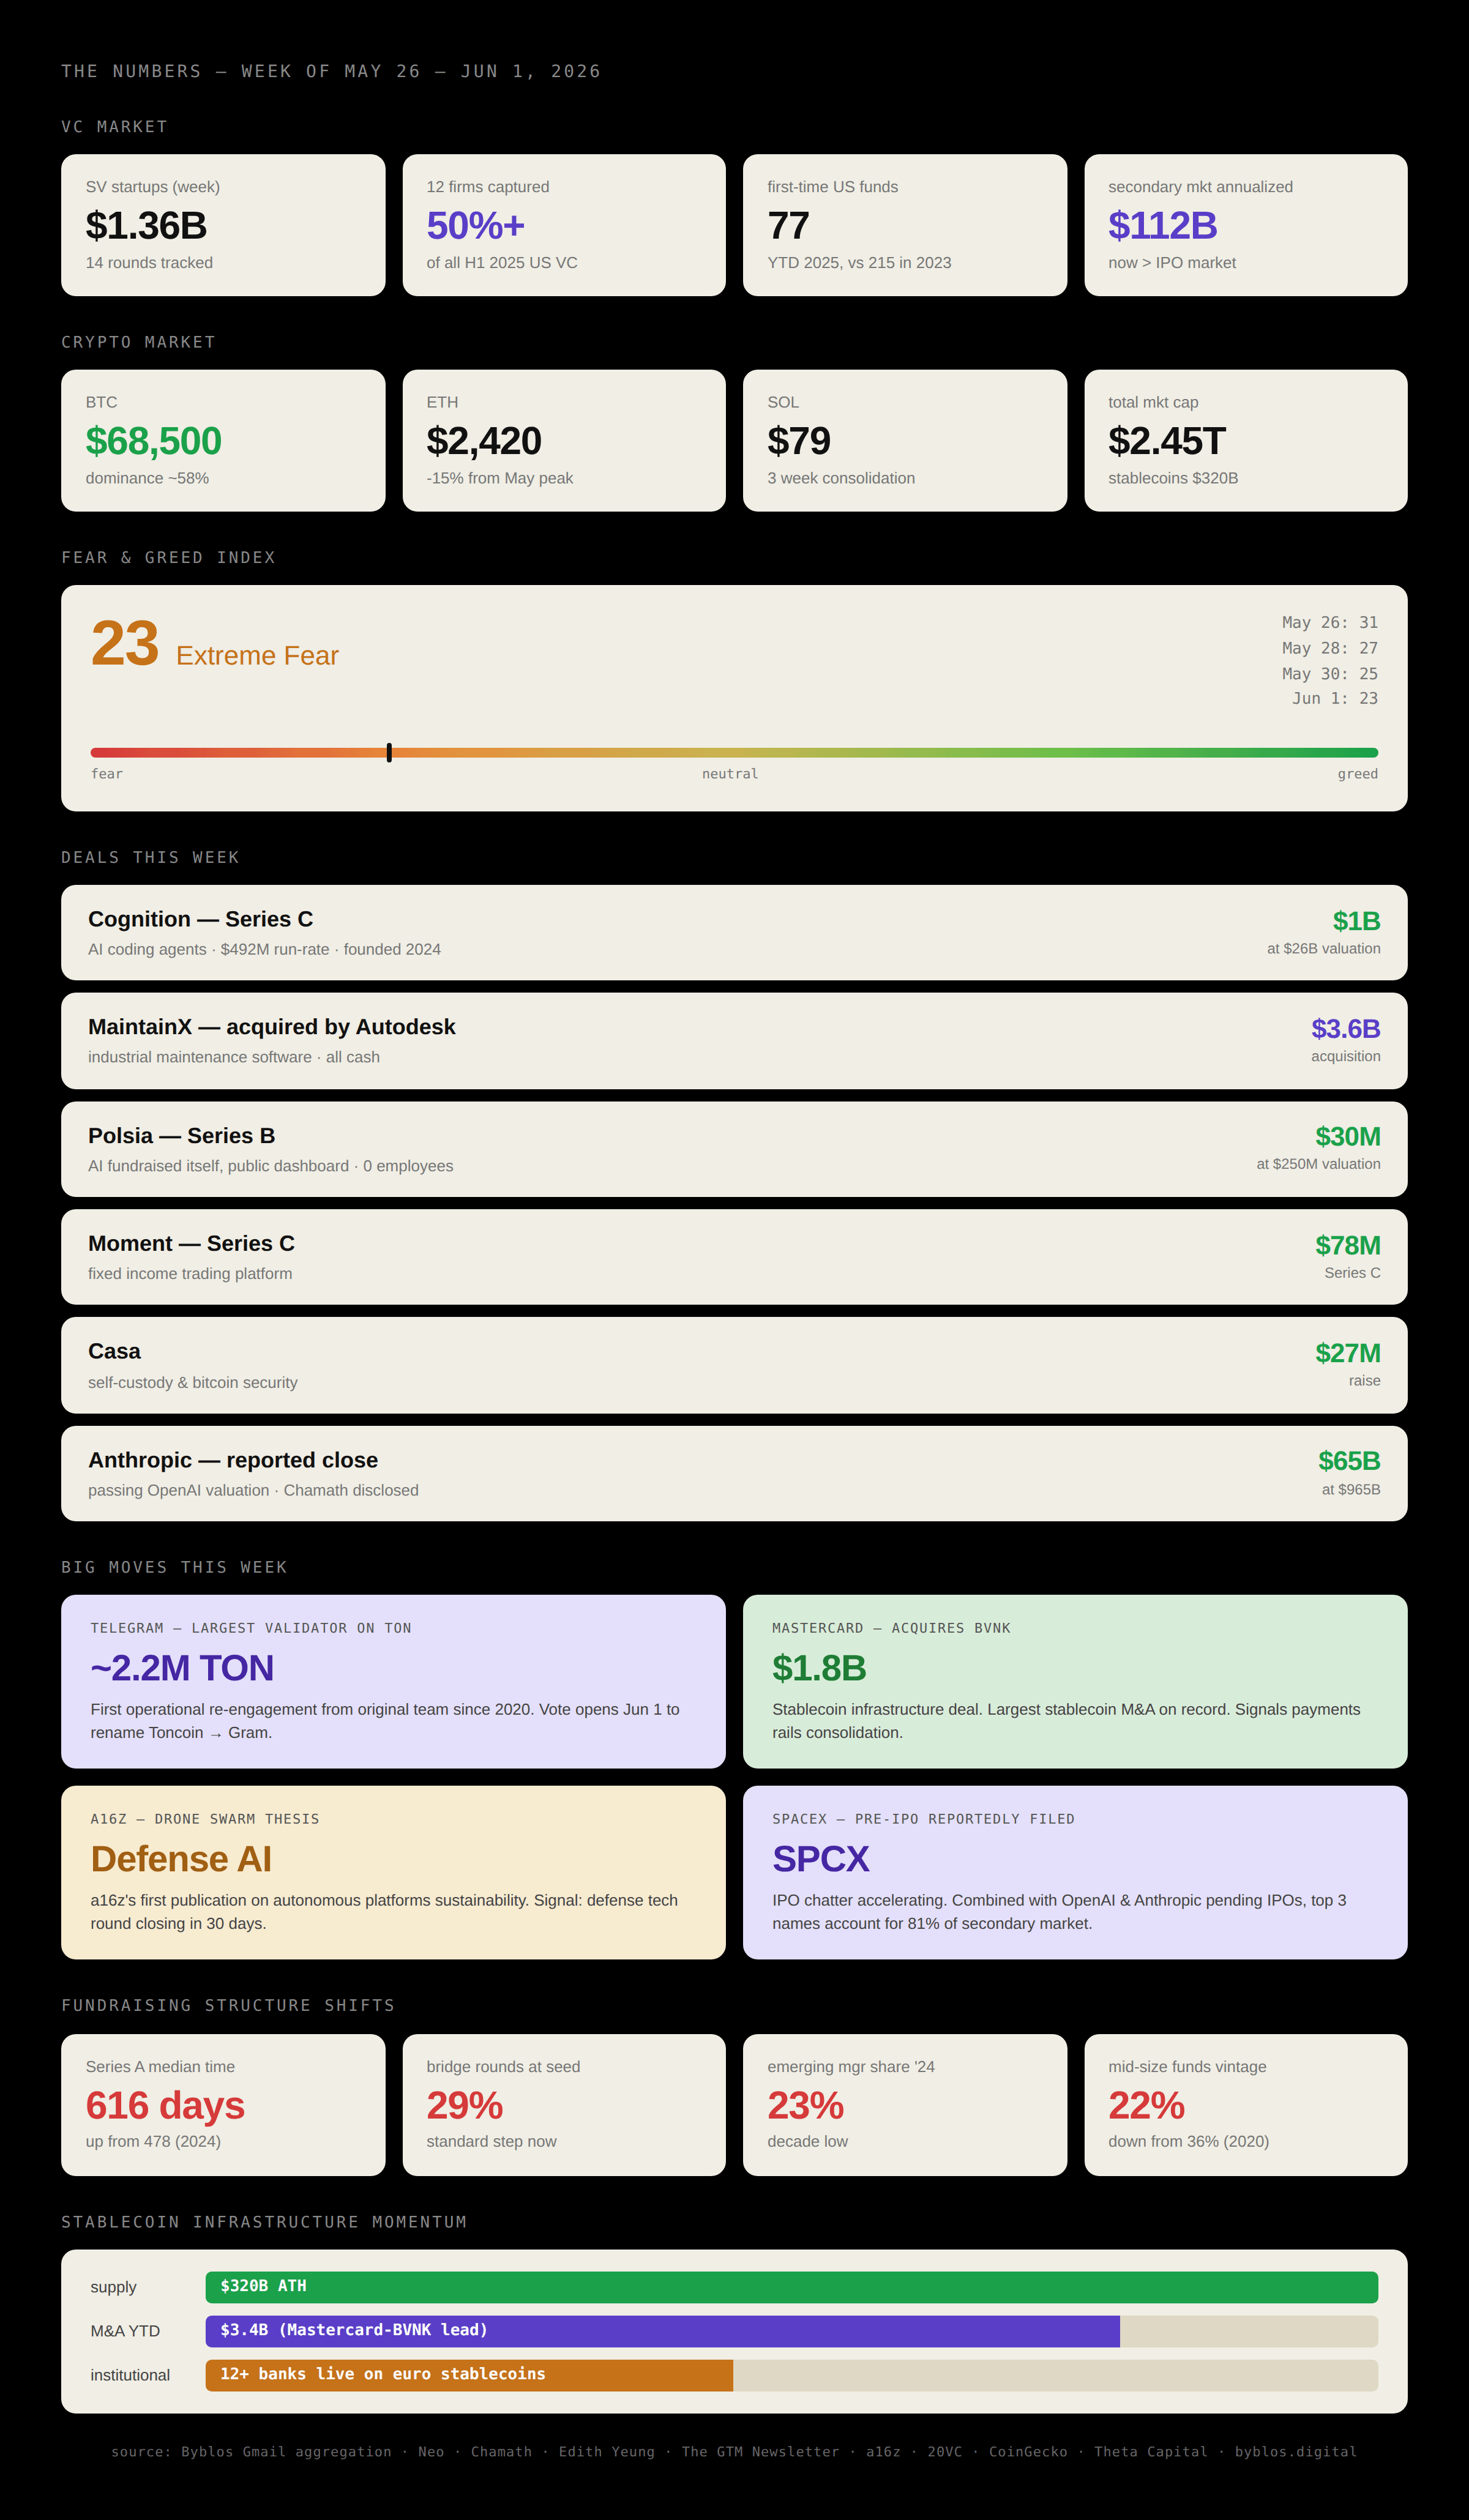
First: Polsia closed $30M at a $250M valuation with 0 employees, running the fundraise itself via AI on a public Twitter dashboard. That's not a normal seed. That's a pre-seed startup pricing like a Series A, skipping every intermediate step. Reported in The GTM Newsletter this week.
Second: Cognition's $1B raise at $26B valuation. Founded in 2024, now at $492M run-rate. They went from Series A to Series C in 18 months. The traditional stage progression — A, then B, then C — is collapsing into "raise as much as you can while you have momentum, before the next round becomes harder."
Third: Edith Yeung's roundup of last week's Silicon Valley deals shows 14 startups raised $1.36B combined. The check sizes cluster around two patterns - very small (under $5M, pre-seed) and very large (over $50M, late stage). The $10-20M Series A round, once the median, is becoming the exception.
The GTM Newsletter piece "The Distribution Era" this week captured what's driving this. The thesis: distribution is now the moat, not product. The companies winning in 2026 are the ones building distribution before product. That changes the fundraise - you're not raising to build, you're raising to acquire users at scale before someone else does.
This rewires the fundraising stack. If distribution is the moat, you need a lot of capital upfront, fast. You can't take three years to get from seed to Series A while a competitor sprints. You raise huge or you don't raise.
What this means for founders:
Stop planning a 4-stage raise. Plan a 2-stage raise.
Stage 1: Pre-seed plus bridge plus extended runway, ideally from specialist micro-funds who can write follow-on checks. Aim for 18-24 months of runway from $1-3M total.
Stage 2: A meaningful Series A only when you have either real ARR ($1M+) or genuine distribution scale (~100K users with engagement). Skip the seed-then-A two-step.
If you can't get to either of those milestones on Stage 1 capital, the seed-then-A path is no longer reliably available to you. The fund that would have written your seed in 2021 doesn't exist anymore, or is too underwater to write checks.
The implication: be much more cautious about scaling team headcount on pre-seed money. The bridge cycle is now longer than founders are budgeting for. Founders who keep their team small and their burn low — even at the cost of slower growth — are the ones surviving the gap between pre-seed and the new Series A bar.
Everything in today’s digest came from the Byblos live feed. The full newsletter archive, the VC directory, and tomorrow’s signal are all waiting for you at Byblos.digital - the investor interned, curated.
Our X (for timely updates and founder/investor opps)
Our Linkedin (for connections and professional insights)
Our app (for VC index cards, the feed of newsletters, and upcoming AI summaries)
That’s the data. Now go build something.